The owner who can open five reports and ask the right questions has more control than the owner who receives a 30-page packet and reads none of it. The goal is not to replace a bookkeeper. It is to recognize when the numbers support a decision and when they need investigation.
Current small business accounting software can make standard reports available without rebuilding them in a spreadsheet. Exact availability and customization can vary by subscription, so check the official report documentation for the plan in use. Whatever the tool, run every report through the same reconciled cutoff date.
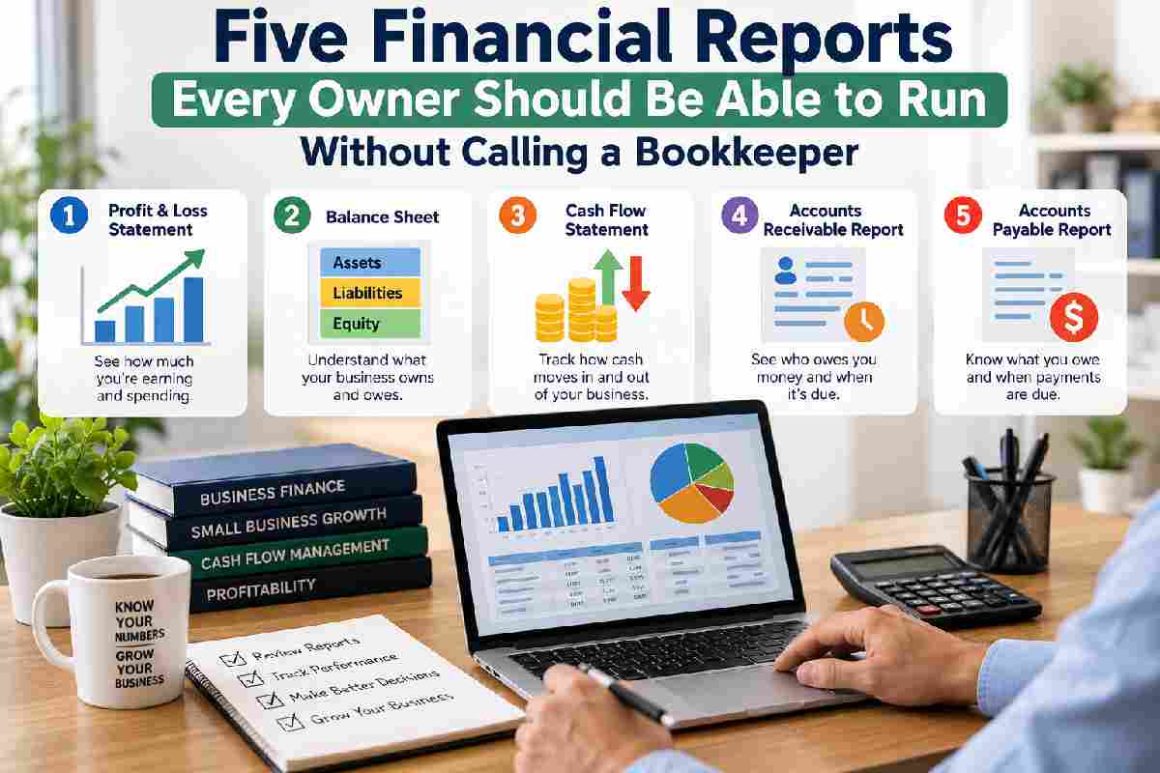
Use this five-report gallery as a decision routine: know the question each report answers, scan a few high-value lines, and follow a surprising number into the supporting detail.
Table of Contents
Start with the decision, not the report name
Before reading, confirm the reporting period, cash or accrual basis, comparison column, and data freshness. A balance sheet is a snapshot as of a date; a profit and loss statement covers a period. The SEC’s beginner guide provides a plain-language explanation of the major statements and how they connect. If bank, card, receivable, or payable balances are not reconciled, treat the output as a draft rather than a decision-ready report.
1. Profit and loss: Are operations earning enough?
What to scan first
Review revenue, gross profit, operating expenses, and net income against the prior period, prior year, and budget. Look at the monthly pattern, not only the year-to-date total. Warning signs include falling margin, expense growth that outpaces sales, large uncategorized amounts, and one-time items mixed with normal operations. Next, drill into the product, service, customer, location, or department that explains the change. Use percentages as well as dollars: gross margin and major expense categories as a share of revenue often reveal deterioration before the absolute amount looks alarming.
2. Balance sheet: What does the business own and owe?
Scan cash, accounts receivable, inventory, prepaid expenses, accounts payable, credit cards, loans, taxes payable, and equity. Stale clearing accounts, negative asset balances, unexplained loan amounts, or receivables that do not match the aging report are signals to stop and reconcile. The balance sheet also reveals obligations that are absent from a quick glance at profit. The SBA’s finance overview describes it as a foundation for tracking assets, liabilities, and equity. Compare the same date across several months, and tie receivables, payables, inventory, debt, and payroll liabilities to their detailed schedules rather than accepting a plausible-looking total.
3. Cash flow statement: Where did cash actually move?
Read operating, investing, and financing activity separately. Operating cash shows how the core business generated or used cash. Investing activity includes equipment and other long-term assets. Financing activity includes borrowing, debt repayment, and owner-related funding. A profitable month can still reduce cash because customers have not paid, inventory was purchased, equipment was acquired, or loan principal was repaid. Ask for an explanation of the largest movements, not every line. Also distinguish cash movements from noncash expenses such as depreciation and from balance-sheet activity that never appears as an operating expense. That bridge is often the fastest way to explain why profit and cash diverged.
4. Accounts receivable aging: Which cash is delayed?
Start with total overdue dollars, the oldest balances, and customer concentration. Then separate genuine late payment from disputes, invoices sent to the wrong contact, missing purchase-order information, unapplied receipts, or credits that should reduce the balance. Compare the aging to the balance sheet; official QuickBooks guidance on matching aging reports illustrates why the summary and customer detail should agree before collections decisions are made.
Aging buckets that need action
Do not use one generic response for every overdue invoice. A recent balance may need a reminder. A disputed item needs an owner and evidence. A long-outstanding balance may require a payment plan, escalation, or write-off review under a documented policy. Track the action and expected cash date in the forecast.
5. Accounts payable aging: What commitments are coming due?
Review overdue bills, large payments due in the next two weeks, duplicate or disputed items, vendor concentration, and credits not yet applied. Compare payment timing with the cash forecast before accelerating or delaying a bill. An unusually old payable can indicate a cash problem, a missing approval, a duplicate, or a vendor dispute; the age alone does not explain the cause. Confirm that approved bills have not been entered twice, that vendor credits are applied, and that payment batches match the bills authorized for release. The report is both a planning tool and an exception list.
Build a 15-minute owner review routine
- Minutes 1-3: Scan the profit and loss statement for revenue, margin, and expense movement.
- Minutes 4-6: Check the balance sheet for cash, working capital, debt, taxes, and unexplained balances.
- Minutes 7-9: Read the cash flow statement and identify the two largest uses of cash.
- Minutes 10-13: Review the oldest and largest receivables and the most important upcoming payables.
- Minutes 14-15: Write three questions, assign follow-up, and decide whether any report is too unreliable to use.
Whether a business begins with free accounting software or a more advanced reporting setup, the foundation is the same: complete records, consistent periods, and regular review. The IRS recordkeeping page explains how organized records support financial statements and tax reporting.
Run, read, and question the reports
Owners do not need to prepare every report, but they should be able to run, read, and question the five reports that explain profitability, financial position, cash movement, delayed collections, and near-term obligations. A short, repeatable review makes those reports part of operating the business rather than paperwork that arrives after the decision.